The Hemp Ban Is Coming—What It Means For Bank Accounts And Loans

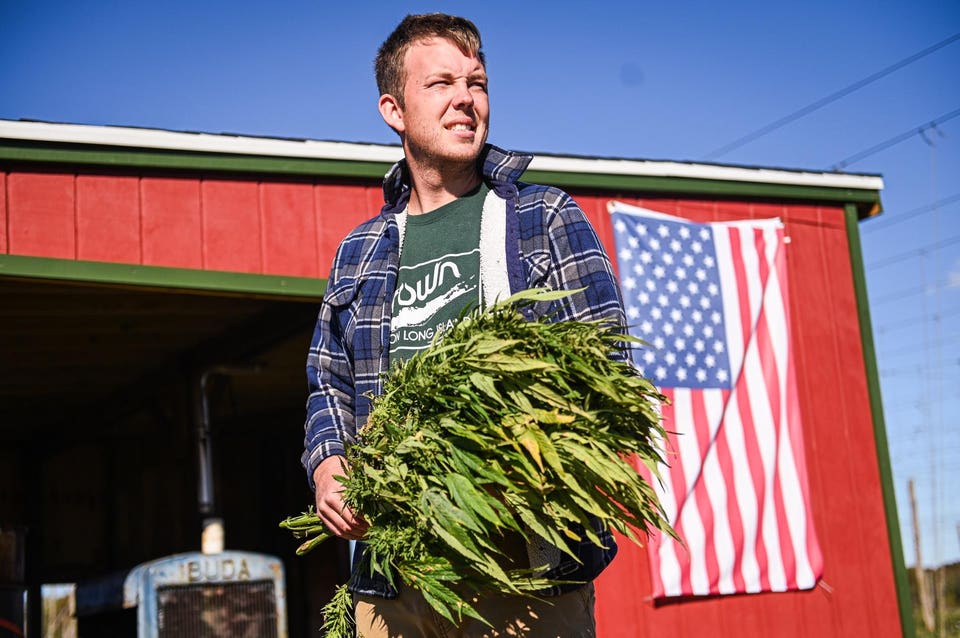
Section 781 of the fiscal year 2026 agriculture appropriations law is the problem
Since the 2018 Farm Bill legalized it, hemp has been treated by some financial institutions as the “safe” cousin of cannabis banking — a federally legal commodity that let banks and credit unions serve plant-touching businesses without wading into Schedule I territory. That distinction is about to blur.
A provision tucked into a 2025 government funding bill rewrites the federal definition of hemp, and unless Congress acts again, most hemp-derived cannabinoid products on shelves today will fall outside that definition this winter. For the financial institutions that bank hemp companies — and the lenders with money already out the door to them — the question isn’t whether the ban matters. It’s what to do about it.
“The looming hemp ban is real, and one that banks and credit unions banking hemp businesses need to take seriously,” says Chris Van Dyck, a partner at Cogent Law in Washington, D.C., who previously served as a financial regulatory attorney at the Maine Bureau of Financial Institutions and as general counsel at Maine-based credit union cPort Credit Union before moving into advising financial institutions on cannabis and hemp banking. Institutions in the hemp space, he says via email, “could potentially find themselves with a group of accounts that is more risky than their cannabis accounts.”
To Read The Rest Of This Article On Forbes, Click Here